



The Pensions Regulator in Ireland expects “considerable” progress to be made in Ireland by the end of 2026.
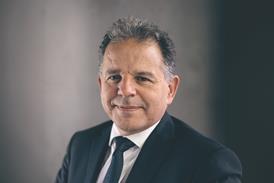
In the statement from the Pensions Regulator’s chief executive officer Brendan Kennedy, the authority highlighted that 93% of scheme assets were held in master trusts or single employer pension funds that plan to continue as standalone schemes as at 1 July 2026.
By the end of 2025, the total Personal Retirement Savings Account (PRSA) assets were €23bn, which represents an increase of 24% in 2025, following an increase of 55% in 2024. As a result, the authority said it is devoting more resources to the supervision of PRSAs.
The current regulations governing PRSA contracts date back to 2002, and the Authority is considering whether they provide an adequate degree of protection for PRSA contributors, and if appropriate, will bring proposals to the Minister for Social Protection.
The Authority has also welcomed the announcement by Minister for Social Protection, Dara Calleary, that authorisation legislation will be published later this year.
The upcoming framework, combined with ongoing scheme consolidation and the expiry of the IORP II derogation for one-member arrangements, aims to strengthen regulatory oversight by the Pensions Authority.
The transposition of IORP II into Irish pensions legislation in 2021 set off a series of changes in Irish pensions which are ongoing. The five-year derogation from the new obligations for pre-existing one-member arrangements expired in April 2026.
Kennedy said that significant progress has been made on the draft legislation and it will be an “important addition” to the authority’s oversight regime.
He added that the Authority has commenced planning for the operationalisation of the authorisation regime.
Kennedy disclosed that all pension schemes intending to remain in operation will have to apply for authorisation and this will be a significant change for the authority and the sector.
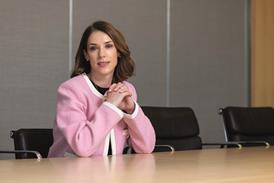
In her chair statement, Fiona Tierney, said: “The Authority has extensively engaged with administrators and trustees to support the considerable work that has already been done to ensure pension schemes meet their compliance obligations, and this work continues. However, there are still trustees who have failed to engage with the compliance process and are leaving themselves open to the risk of prosecution by the Authority.”