If you’ve felt there’s something different in the air these days, you wouldn’t be alone. No, it’s not the whiff of end-of-summer, back-to-school vibes, nor is it the fading emotions of the World Cup. It’s something far more consequential. The rise of the UK asset owner. Quietly at first, and now at scale, a new generation of large UK pension asset owners is beginning to reshape how capital is allocated and who makes the key decisions.
Until recently, the UK had just one asset owner among the world’s 100 largest. Soon it will likely have six to eight. Together, those organisations will manage close to half a trillion pounds of assets, with several among the fastest-growing asset owners globally. In scale and influence, they are beginning to resemble the Australian super funds, Canadian pension plans and Scandinavian institutions that have long shaped global investment markets.
Asset owners bring real agency to the investment world. Most importantly, they create a clearer connection between investment decisions and member outcomes. When decision-making sits closer to the ultimate fiduciary, there is less room for preferences, incentives and accountability to become diluted along the way, as they can in longer, more fragmented investment chains.
They’re the ones who can say: “We’re responsible. We’re thinking long-term. And we’re doing this for members.” But to do that properly, they need the right structures: segregated mandates that put them in control, aligned partners to deliver them, and clear standards to guide the relationship.
Products vs partnerships
This is where the role of asset managers must evolve. The old model of siloed products sitting on a shelf and selected from buy-lists is increasingly inadequate. Large asset owners need integrated solutions rather than individual products. They need asset managers who can connect capabilities across global teams, work collaboratively on strategy design and adapt as the asset owner’s own operating model evolves.
It means placing relationship managers at the heart of the operating model not just portfolio managers. Everyone assumes they are doing that, but the reality is much harder than many give it credit for. When it’s done well it’s really good, but this practice is not universal.
Having worked through six multi-billion-pound segregated mandate creations over the last two years at People’s Pension, I’ve become convinced that a segregated mandate is not simply a different investment vehicle. Done properly, it creates a fundamentally different relationship between asset owner and asset manager, one based on partnership, alignment and shared responsibility for outcomes.
This is a call to action for asset managers. Partnership is not a buzzword; it’s a new operating model.
Before going further, it’s worth being clear about what we actually mean by an asset owner. What is an asset owner? Definitions vary but four key factors stand out:
- Being the ultimate fiduciary of assets (as opposed to acting under a delegated mandate or under the guidelines of a commingled investment vehicle),
- Ability to act solely in the best interest of members,
- A societal license to operate, and
- Delivery of mission-level outcomes (e.g. pension payments) as opposed to investment mandate-related outcomes.
If asset ‘owner-isation’ is the trend, scale is the engine behind it.
The benefits of scale
In broad terms, asset management is a scale game – it generally does not require 10x the resources to manage 10x the assets. In a fragmented world, the benefits of scale accrue to asset managers and providers. In a more focused asset-owner-driven world, this can accrue to the asset owners and by extension, their beneficiaries.
Capability
Scale by itself probably leads to more of the same but bigger. One key ingredient for really making a difference is the ability scale gives asset owners to build internal capability to sit as principal, steering those working on their behalf such as asset managers. That capability needn’t necessarily displace the role of asset managers but can equally sit alongside it and complement it.
Asset owner-isation is therefore less about internalisation and more about ownership of decisions, ownership of outcomes and ownership of fiduciary responsibility.
Member outcomes
Ultimately, the rise of the UK asset owner is not an industry story. It is a member story.
The purpose of building larger, more capable asset owners is not to create impressive institutions or to emulate overseas pension systems for their own sake. It’s to improve outcomes for the millions of UK workers whose savings these organisations steward.
When scale is combined with strong governance and internal capability, asset owners can negotiate better economics, access a wider opportunity set, take a genuinely long-term view and align investment decisions more closely with member needs. They can focus not simply on outperforming a benchmark, but on delivering the outcomes that matter: better retirement incomes, greater financial security and confidence that members’ capital is being managed in their interests.
The asset owner-isation of the UK is well underway, and its direction is becoming clear. The institutions that succeed will be those that combine scale with capability, and put members’ interests first in everything they do. If they are successful, the biggest winners will not be the funds themselves, nor the asset managers that serve them, but the millions of hard-working savers whose futures depend on getting these decisions right.
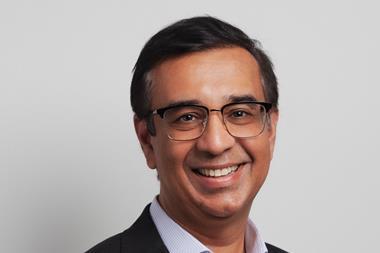
Dan Mikulskis is the chief investment officer of People’s Partnership