
European pension funds have been rethinking how they collaborate with partners and suppliers, along with how much risk they can carry. From bespoke indices to M&A, schemes have been grappling with what they build themselves and what they outsource, all while regulators loosen the rules and equity risk comes under fresh scrutiny.
Benchmarks and indices
APG Asset Management and Swiss Life Asset Managers backed the launch of a new equity index range, the STOXX Investable Market Indices (IMI), which the provider says captures nearly all of the investable equity universe and consists of building blocks institutional investors can use to build their required benchmark.
APG Asset Management, which counts the €568bn Dutch pension fund ABP among its clients, is using the new IMI framework as a benchmark solution for a €20bn emerging markets equity allocation, STOXX said.
Elsewhere Fonds de Réserve pour les Retraites (FRR), is persuing a bespoke indexing solution with BNP Paribas Asset Management.
The €20.7bn French public sector fund has invested €100m in a new climate transition index strategy that it developed in partnership with BNP Paribas AM in a bid to overcome perceived limitations of existing indices.
Dubbed the BNP Paribas FRR Eurozone Advanced Transition Equity Index, the new index sets out to identify large- and mid-cap companies best positioned to successfully achieve their climate transition, taking into account both their current emissions footprint and their future financing and implementation capacity.
The new index is being implemented within FRR’s equity index replication mandates, which the reserve fund manages to align with the goals of the Paris Agreement. FRR said this supports the commitments it has made as part of the UN-backed Net-Zero Asset Owner Alliance.
Service providers and ownership
In the UK, NEST focused on infrastructure rather than index design and explains how it is expanding its data and technology capability with custodian Northern Trust as it approaches £100bn in assets under management (AUM).
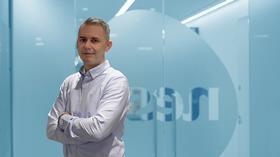
With NEST’s investment operations team consisting of only “six or seven people”, chief operating officer, Paul Todd, said the scheme deliberately sought a custody partner able to fill capabilities it could not build efficiently in-house, including “understanding how data flows, understanding what our underlying assets [are] … how we deconstruct our portfolios.”
Rather than develop those capabilities internally, NEST decided to rely on Northern Trust. Todd said: “Why wouldn’t we do that with our custodian and fund accountants if we could find the right partner?”
In M&A news, CalPERS has joined a consortium buying Russell Investments.
CalPERS’ deputy chief investment officer Anton Orlich said Russell had built a trusted global franchise “grounded in investment excellence and client service”.
Headline appointments

Swedish occupational pension giant Alecta appointed its asset management head Pablo Bernengo as its new chief executive officer. The announcement comes after Alecta’s CEO Peder Hasslev announced he will leave the Swedish occupational pensions giant in the autumn to retire. Bernengo will take up his position on 1 September.
In the Netherlands, Alineke van den Berge-Blindenbach has been appointed CEO of APG Asset Management.
The appointment of Van den Berge-Blindenbach follows APG’s renewed strategy announced at the end of 2025, which centres around two business units – pension services and asset management.
Asset allocation
Two pension markets came up with different solutions to the same challenge; how much equity risk is too much to carry through a period of flux?
Dutch pensions giant ABP revealed it is not hedging its significant equity risk in the six-month run-up to the transition of its €518bn scheme for civil servants to defined contribution (DC) from defined benefit (DB) — because it is not deemed worth the expense.
The announcement follows ABP receving formal approval from the Dutch central bank (DNB) for its transition plan, which is set to take effect on 1 January 2027, as part of the Dutch pensions reform.
The amount the Netherlands’ largest pension fund can distribute in DC pension assets to its three million participants on that day depends on its financial position at the time, with a higher funding ratio allowing it to distribute more, and a lower one leaving less to share out. At the end of May, ABP’s funding ratio stood at 126.6%.
In an interview with IPE’s sister news service Pensioen Pro, ABP executive board member Yolanda Verdonk-van Lokven said the pension fund was not taking extra measures to limit its equity risk in the meantime.
“It does indeed state that options involving derivatives are of limited feasibility, given ABP’s size. Physically selling off shares entails significant costs and disadvantages,” she said.
Meanwhile, Switzerland’s schemes have been wrestling with diversification conundrums.
Swiss Pensionskassen have decided to reassess the equity risk in their portfolios, as they contend with low domestic interest rates, higher global inflation expectations and increasing concentration risks in developed and emerging market indices.
Bernische Lehrerversicherungskasse (BLVK), the CHF9.2bn pension fund for teachers in the canton of Bern, increased its equity exposure by around CHF300m year on year in 2025 to CHF3.55bn, according to its 2025 financial statements.
Meanwhile, Basellandschaftliche Pensionskasse (BLPK), which invests around CHF4bn in Swiss and global equities, has also reviewed its investment strategy, slightly increasing its equity allocation to take on additional risk.
Home Bias
Denmark also grappled with its own diversification issue and concluded there has been too little abroad.
New figures found that the significant home bias in Danish pension fund portfolios decreased last year, but remains far larger than warranted by the comparative size of the country’s economy and stock market, according to a recent analysis by Insurance & Pension Denmark (IPD).
The lobby group’s figures revealed that total investments in Denmark by the country’s pensions sector dipped to DKK1.902trn (€254bn) in 2025, down 3% from the year before, but at 38% of portfolios on average, still far outweighed allocations to the EU outside Denmark and to the US – geographical weightings which stood at 21% and 27%, respectively.
Private markets
Private markets saw funds moving in the opposite direction, opting to add exposure.
Enpam, the €30bn pension fund for doctors in Italy, said it was investing €220m in domestic venture capital (VC) and small and mid-cap equities.
The pension fund’s board has approved a €120m commitment to the Fondo Nazionale Strategico Indiretto (FNSI), the state-backed strategic investment vehicle managed by Cassa Depositi e Prestiti (CDP).
Enpam’s board has also approved a further €100m commitment across 10 VC funds.
According to the pension fund, the VC funds will invest in sectors including healthcare and biopharma to support the Italian real economy.
In the UK, NEST committed £200m (€230m) to high-growth companies through the creation of a dedicated venture capital (VC) sleeve with Schroders Capital.
The move builds on the £68bn master trust’s existing private markets strategy and investment in high-growth companies. NEST said the new VC sleeve will formalise and scale its approach, providing access to companies backed by Schroders Capital.
The commitment forms part of NEST’s wider ambition to increase private markets exposure to 30% by 2030.
Meanwhile, analysis by the UK’s Pensions Regulator (TPR) found that only one in five UK master trusts allocate more than 5% of default assets to private markets, despite around 60% having some exposure to the asset class.
The analysis comes as the occupational DC market expanded by 22% in assets and 7% in membership during 2025. Master trusts now account for more than 83% of DC assets and 92% of memberships.
Regulation spotlight
Regulators, meanwhile, have been considering how much freedom funds should have in making these calls.
Icelandic pension funds have been granted more asset allocation freedom under a raft of changes to their investment rules, which took effect in July.
Arne Vagn Olsen, chief investment officer at the Pension Fund of Commerce (Lífeyrissjóður verzlunarmanna, LV), said in an article in Icelandic daily Morgunblaðið that investment restrictions on Icelandic pension funds had previously been somewhat at odds with those in force in many other places.
“In other countries, the general rule is that pension fund investments follow the so-called prudent person principle, which means that the funds have more freedom to manage assets but bear greater responsibility and have to account for their investment decisions more clearly,” he told the paper.
In the UK, the Pensions Regulator (TPR) mapped out its direction for the next five years, supporting implementation of the UK government’s pension reform agenda.
The regulator highlighted that while auto-enrolment has transformed retirement saving, with 23 million people now saving into a workplace pension, 15 million working-age people are still undersaving.
For this reason, TPR said its new corporate strategy is centred around sustainable income in retirement, supported by a pensions system that provides security and value for all.
Meanwhile, the Italian pension regulator Covip relaxed the investment criteria pension funds must follow when designing life-cycle investment options under the country’s auto-enrolment regime, while extending the transition period for schemes to comply with the new requirements.
The changes follow a consultation launched in April, in which Covip proposed requiring life-cycle strategies to hold a minimum 65% allocation to equities for younger members, falling to 15% as members approached retirement. The consultation also envisaged a six-month transition period.
Stories we are keeping an eye on
German pension funds have been drawn further into the long-running cum-ex and cum-cum tax scandal as BaFin assesses potential liabilities across the financial sector.
‘Cum-ex’ and ‘cum-cum’ are complex, predatory dividend tax arbitrage and tax evasion schemes that exploited loopholes in European dividend withholding tax systems. Both terms originate from Latin, where ‘cum’ means “with” (shares with dividend rights) and ‘ex’ means “without” (shares ex-dividend).
The withholding tax fraud scandal, regarded as one of the largest in German history, has also prompted BaFin to assess the potential financial impact of ‘cum-cum’ and ‘cum-ex’ arrangements on supervised firms.
According to BaFin’s analysis published last week, the total potential financial burden for insurers and pension funds, credit institutions, and securities firms amounts to €7.01bn.
Representing around €450bn in assets, they argue that investment decisions must remain driven by prudence, diversification and long-term solvency rather than political targets.
It comes at a time when the EU’s SIU is looking to mobilise pension capital for European growth and competitiveness, prompting pension groups to stress that greater domestic investment should be enabled rather than mandated.

Topics
- ABP
- Alecta
- APG Asset Management
- Asset Allocation
- Asset Managers
- BaFin
- BLPK
- BNP Paribas Asset Management
- CalPERS
- Covip
- Defined contribution
- Denmark
- Enpam
- Equities
- European Union
- Fondo Nazionale Strategico Indiretto (FNSI)
- Fonds de réserve pour les retraites (FRR)
- Iceland
- Insurance & Pension Denmark (IPD)
- Mandates
- NEST
- Netherlands
- Northern Trust
- People moves round-ups
- Reform & Regulation
- Savings and Investments Union (SIU)
- Sweden
- Switzerland
- The Pensions Regulator (TPR)
- United Kingdom